
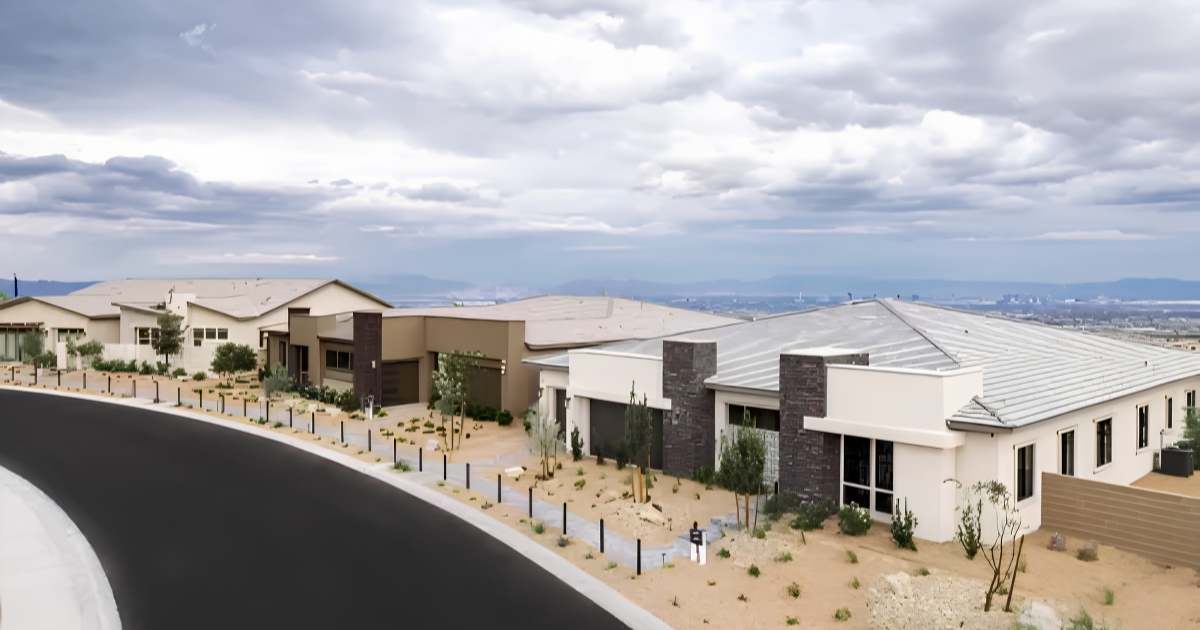
Bay Area → Las Vegas · Relocation guide
Moving from the Bay Area to Las Vegas
At the Santa Clara County median of $1,920,000, a seller with a $400,000 loan nets roughly $1,385,000 after costs. That buys a $700,000 Las Vegas home outright and leaves $685,000 invested. This is the largest equity release of any California region — and if you hold RSUs, the sourcing question matters as much as the house.
Bay Area median
$1,920,000
September 2026
Las Vegas median
$475,000
25% of the Bay Area
The gap
$1,445,000
At the median
Equity released
~$1.39M
At the Santa Clara median, after costs
Nevada income tax
None
No personal, corporate or franchise tax
What you gain
The equity
What $1,920,000 turns into here
| At the Bay Area median | |
|---|---|
| Sale price | $1,920,000 |
| Remaining loan | −$400,000 |
| Selling costs at roughly 7% | −$134,400 |
| Net proceeds | $1,385,600 |
An illustration using the September 2026 county median and an assumed loan balance. Your own figure depends on your balance, your sale price and your actual costs.
| What you do | Financing | Monthly P&I | Cash left |
|---|---|---|---|
| Buy a $700,000 home | Outright, no loan | $0 / mo | $685,600 left over |
| Buy a $1,000,000 home | Outright, no loan | $0 / mo | $385,600 left over |
Principal and interest only at an illustrative 7%, before taxes, insurance and any association dues. Not a rate quote.
The scale of it
Buying outright is a realistic option here
At the Santa Clara median a seller clears enough to buy a $700,000 Las Vegas home with no mortgage and still have $685,000 left. At the San Mateo median it is over a million left over.
That changes the conversation from what can you qualify for to what do you actually want, and how much should stay invested. It is a better problem, and it is worth planning rather than improvising.
Monthly
What you keep each month
The household budget and the California income tax change at the same time. Comparisons that show only the first understate the move considerably.
| Monthly category | Bay Area | Las Vegas | Change |
|---|---|---|---|
| Rent | $4,200 | $2,700 | −$1,500 |
| Utilities and internet | $300 | $450 | +$150 |
| Transportation and insurance | $650 | $1,050 | +$400 |
| Health costs and child care | $1,700 | $1,600 | −$100 |
| Food and household | $1,200 | $1,100 | −$100 |
| California visits and travel | $100 | $600 | +$500 |
| Budget change | $8,150 | $7,500 | −$650 |
An illustrative household comparison, not regional price quotes. Running the air conditioning and driving a wider valley are real costs, and they belong in the table.
Then the tax
| Household income | Single filer | Married filing jointly |
|---|---|---|
| $150,000 | $1,469 / mo | $1,128 / mo |
| $200,000 | $1,857 / mo | $1,513 / mo |
| $250,000 | $2,244 / mo | $1,901 / mo |
The budget change above plus California state income tax no longer paid, on 2026 California brackets and standard deductions. Illustrative: your figure depends on filing status, deductions, credits and income source. Nevada residence does not change federal tax.
A full relocation runs around $16,000 — transport, packing, travel, temporary housing, deposits, initial furniture and a contingency.
At $150,000 jointly it is nearer 14 months. Every month after that is yours.
Your part of the Bay Area
It is not one move
What changes depends on where you are leaving
Bay Area is not a single housing market or a single way of living, and the move looks different from each part of it. Find yours below.
San Francisco
The city itself
Compare the whole urban routine, not just the house. If you walk, cycle or take transit for groceries, work and social life, a suburban Nevada home adds a vehicle and a lot of driving. An extra room does not replace street-level convenience or a neighborhood network.
Look at central Las Vegas, the Arts District and suitable condo locations alongside suburban options, and walk the routes you would actually use. Restaurant density does not establish that daily errands work without a car.
If your rent is unusually low or under local protections, compare that actual payment rather than a citywide asking rent, and understand what returning would cost before you give it up. For owners, a detached home, a condo and a tenancy-in-common interest produce quite different proceeds and replacement costs.
San Mateo County and the Peninsula
Daly City, South San Francisco, San Mateo, Burlingame, Redwood City, Menlo Park
Separate access to an employer campus from access to SFO. A return flight still leaves ground travel, and the right airport changes with the final office or family address.
Summerlin, Green Valley Ranch and Inspirada are the usual shortlist for layout, parks and services. Confirm the specific school's program and assignment rather than trying to match a Peninsula city by reputation.
If you are a high-equity owner, estimate proceeds after payoff, expenses and tax before fixing a Nevada price point, and keep money available for care, travel and future repairs. Buying a large home for cash lowers debt while leaving real operating costs and less accessible savings.
San Jose and the South Bay
San Jose, Santa Clara, Sunnyvale, Mountain View, Cupertino, Campbell, Los Gatos
Settle work geography early. Software tasks, laboratory work, hardware testing, manufacturing and client access carry very different attendance requirements — get an approved Nevada arrangement or a real local offer in writing.
Compare base salary separately from bonus and equity. A geographic pay adjustment or a lost future grant can offset a large part of the housing saving, and that arithmetic belongs in the decision rather than after it.
Existing awards may still require California sourcing analysis after you move. Keep compensation documents and workday records rather than relying on the date the shares were sold. This is the single most expensive thing for a South Bay household to get wrong, and it is worth a CPA before the move date is set.
Oakland, Berkeley and the inner East Bay
Oakland, Berkeley, Alameda, Emeryville, Richmond, El Cerrito
Identify the features you actually use: a compact center, transit, waterfront, a university, specific food businesses, arts, established relationships. A larger detached house can change several of those at once.
Look at central Las Vegas and established neighborhoods as well as master-planned communities, and test the property, block and routes at different times of day. Visit the shops, places of worship, organizations and activities that matter to you rather than reading a broad neighborhood label.
Condo owners should compare association finances, insurance, reserves and possible assessments on both sides. If you currently share a home or manage without a car, model living independently and any new vehicle separately from the move itself.
Fremont, Tri-Valley and inland Contra Costa
Fremont, Pleasanton, Dublin, Livermore, San Ramon, Danville, Walnut Creek, Concord, Brentwood, Antioch
Use your current property's actual costs. These markets and commute patterns vary a great deal, and familiarity with inland heat does not establish comfort with a Nevada home's cooling needs or summer nights.
Summerlin, Green Valley, Inspirada and Anthem are all worth comparing, with school and workplace checks at the precise address. A newer home can carry association layers, unfinished landscaping and costs beyond the advertised price.
If you currently trade a long Bay Area commute for a larger home, define what this move has to change. Repeated flights back to an office recreate the same time burden in another form.
Marin, Sonoma, Napa and Solano
San Rafael, Novato, Mill Valley, Santa Rosa, Petaluma, Napa, Vallejo, Fairfield, Vacaville
Marin households should test the loss of the current outdoor setting and the longer journey from a Bay Area airport. Santa Rosa, Petaluma, Sonoma and Napa households should compare the actual property and goals rather than assuming every Bay Area starting budget is similar.
Vallejo, Benicia, Fairfield, Suisun City and Vacaville households often start from a different housing cost and travel pattern than the Peninsula. Use your existing payment, local job and family connections as the baseline.
For land, RVs, animals or a workshop, verify zoning, utilities, access and association rules on a specific parcel. For a retirement or resort setting, inspect the community, fees, health access and daily services rather than treating it as an equivalent to wine country.
Work & income
Settle this first
Equity compensation is the part that gets expensive
The housing math only holds if the income does. This is the part we see households resolve last, and it should be first.
Get written employer approval for Nevada, with compensation treatment, required Bay Area attendance, travel reimbursement, benefits and what happens if remote status ends. For laboratory, hardware and manufacturing roles, establish which duties genuinely require the site.
Separate base salary from bonus and equity before you compare anything. A geographic pay adjustment or a lost future grant can absorb much of the housing saving, and a household that models only base pay will overstate the move.
Vested and unvested awards can carry California sourcing consequences after you leave, tied to where the work was performed during the vesting period rather than where you lived when you sold. Keep compensation documents and workday records, and get this modeled before you set a move date.
Ask what happens if attendance rises, geographic pay changes, the grant does not repeat, or the role ends.
Would you look for local work, travel more, keep a Bay Area base, or return? With proceeds this size you have more room than most households to absorb that — which is exactly why it is worth deciding deliberately rather than by default.
The city
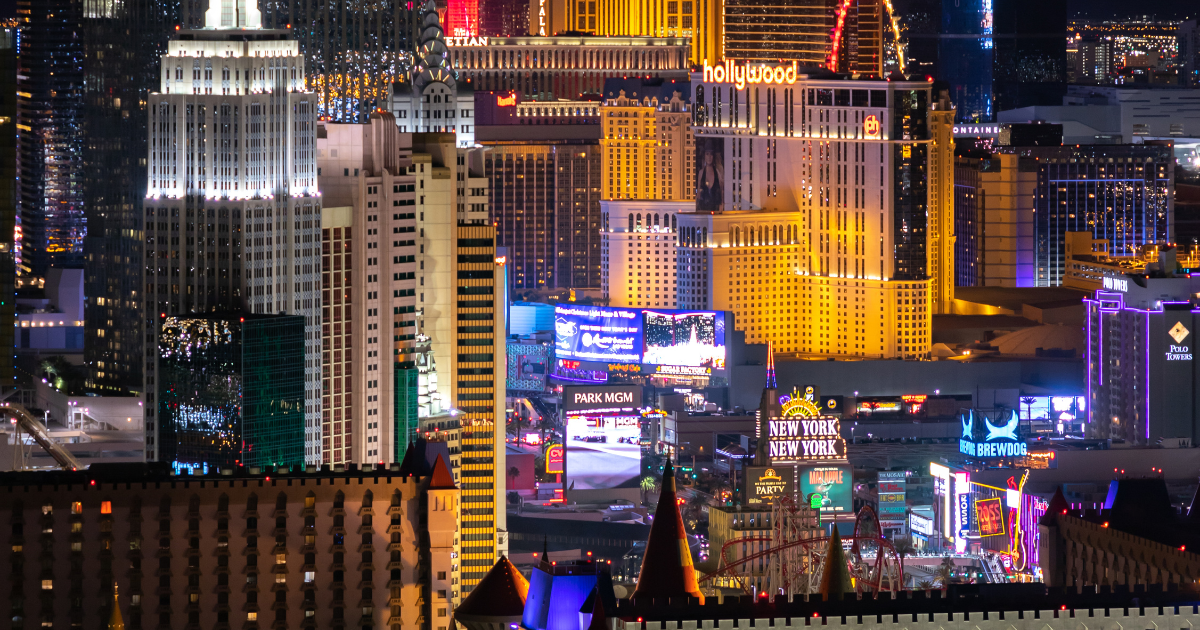
A short flight and a much lower cost base
Bay Area households keep more California ties than most, and the route is frequent and cheap.
What you gain beyond the house is a city whose dining, entertainment and professional sports run well above its population, because tourism supports them.
Where to land
The valley
Areas to investigate
Starting points rather than rankings. Build the shortlist around ordinary life — the work route, the school run, the weekly shop — rather than around a community name you have read about.
| Area | Why it comes up for you | Main checks |
|---|---|---|
| Summerlin | The default shortlist for Peninsula and South Bay households | Village, dues, school assignment, work route |
| Green Valley & Green Valley Ranch | Established services and mature streets; suits inner East Bay buyers | Home systems, school route, traffic, association layers |
| Inspirada, Anthem & Seven Hills | Newer stock and elevation; common for Tri-Valley households | Exact subdivision, elevation, fees, daily travel |
| Southwest valley & Enterprise | Wide price range; establish the jurisdiction before assuming services | Jurisdiction, construction, road access, noise |
| Southern Highlands & Mountain's Edge | Planned southern settings with similar governance to a Bay Area HOA | Work access, rules, fees, completed home cost |
| Northwest & Centennial | Larger parcels for land, animals, RVs or a workshop | Zoning, permitted storage, services, commute |
| North Las Vegas incl. Aliante | Lower entry point; relevant if you are buying outright and banking the rest | Specific location, workplace access, condition, dues |
| Downtown & Arts District | For San Francisco and Oakland households trying to stay car-light | Walking routes, groceries, parking, building finances, noise |
| Cadence & Lake Las Vegas | Resort and east-valley settings; verify fees and daily errands | Daily services, fees, amenities, intended use |
Characteristics rather than rankings. Henderson students generally use Clark County School District's address and enrollment system — a Henderson address is not a separate city school district or a guarantee of a particular campus.
Where we come in
You know the county. We know the valley.
Most Bay Area households we work with have already decided. What they need is someone who can match the area to how they actually live, deploy the proceeds into the right house, negotiate with a builder, and make sure nothing gets left on the table in year one.
Questions
Bay Area to Las Vegas, answered
What does my Bay Area equity buy in Las Vegas?
How much do I actually keep each month?
How long before the move pays for itself?
I have a 3% mortgage. Does the move still work?
How bad is the summer coming from Bay Area?
Where do Bay Area households usually end up?
How are my RSUs taxed if I move to Nevada?
Which Bay Area county does the headline figure use?
Keep reading
More for people moving here
Start here
California to Las Vegas
Taxes, residency, selling or keeping your home.
Where
All 30 Summerlin villages
The west valley, village by village.
Budget
Cost of living
Beyond the mortgage payment.
Comparison
What $400k buys here
Against the rest of the west coast.
Choosing
Evaluating a neighborhood
The checks that are not on the listing.
General
Las Vegas relocation guide
What to sort out before and after you arrive.
Sources and currency
Bay Area median: September 2026 county figure. Las Vegas median: our own November 2026 market update. California income tax figures calculated on 2026 California brackets and standard deductions. Clark County property tax caps: Clark County Assessor. California residency and sourcing: California Franchise Tax Board.
Budget comparisons, equity scenarios, loan illustrations and tax savings on this page are illustrative assumptions for hypothetical households, not price quotes, rate quotes or predictions. Tax rules depend entirely on your own facts. Nothing here is tax, legal or lending advice — we are real estate agents, and the residency and sourcing questions need a qualified tax adviser.